

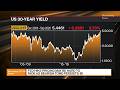
Current global benchmark interest rates between 3% and 6% represent a return to historical norms, yet market sentiment remains fragile following a generation of near-zero rates. Rising bond yields are currently driven by a confluence of a "hotter-than-expected" US economy and hawkish signals from FOMC members regarding persistent inflation. This volatility is exemplified by a recent five-year Treasury auction, which ranked as one of the worst on record due to investor reluctance amid fiscal uncertainty. While short-term volatility has spiked, long-term fundamentals suggest yields are fairly priced given consistent growth and 2.5-3% inflation. Potential stabilization may emerge from a Federal Reserve recommitment to suppressing inflation or the historical tendency for fiscal deficits to improve under a split government following the upcoming election. Despite the recent sell-off, the market has not decoupled from fundamental economic data.
Sign in to continue reading, translating and more.
Open full episode in Podwise